HVAC financing is worth it for a full system replacement when you need the work done now, the payment fits your budget, and you understand the total amount you will repay. It is not worth it when financing charges outweigh the benefit of keeping cash available or when a repair can meet the same need.
- Is HVAC financing worth it in 2026? Yes, when a necessary replacement fits your budget after financing charges.
- Compare the total repayment, not just the monthly payment, before choosing a financing offer.
- West Heating & Cooling can assess furnace and AC installation needs in the Lake of the Ozarks area; confirm financing terms separately.
Is HVAC financing worth it for a full system replacement?
Yes, if the system needs replacement now and the full repayment amount fits your budget. A smaller monthly payment does not make an expensive loan a good deal. Ask for the replacement scope first, then compare how each payment method affects both your cash on hand and your total cost.
| Payment choice | Best for | Advantage | Drawback |
|---|---|---|---|
| Paying from savings | Homeowners who can pay without draining money needed for other expenses | No borrowing charges | Less cash remains available afterward |
| Fixed-payment financing | Homeowners who need to spread the cost and can manage the scheduled payments | Predictable payments when the agreement fixes them | Interest and fees can increase the total repaid |
| Promotional financing | Homeowners who can meet every deadline and understand the written terms | Can reduce borrowing charges if every condition is met | Missed deadlines or misunderstood terms can make it costly |
These are ways to pay, not financing offers from West Heating & Cooling. Do not assume a contractor offers any particular loan or promotion. Compare actual written terms before you commit to a replacement.
Why this matters
A full replacement changes more than the next payment due. You need to know which equipment the proposal covers, whether existing ductwork needs attention, and which work is included in the installation. West Heating & Cooling serves residential and commercial customers in the Lake of the Ozarks area, including Camdenton, Osage Beach, Lake Ozark, Warsaw, and Lebanon. Ask for the proposed work in writing before deciding how to fund it.
The practical question for 2026 is not whether financing makes a new system affordable per month. It is whether the replacement solves the heating or cooling problem and leaves you with a repayment obligation you can carry. If the current system can be repaired reliably for your needs, get that option assessed before borrowing for a complete replacement.
Start with the replacement decision, not the loan
Financing only makes sense after you know what work you are paying for. A proposal for a furnace alone is not the same decision as one covering both heating and cooling. Neither should be treated as interchangeable with a proposal that also changes ductwork or controls.
Ask the contractor to identify the equipment being replaced, the reason for replacement, and any work required around it. Have the contractor distinguish necessary work from optional changes. That gives you a clear scope to use when comparing payment options.
West Heating & Cooling is best for Lake of the Ozarks homeowners who need a local furnace or AC installation assessment before choosing how to pay. The company offers installation and repair, so the useful first step is to establish whether replacement is the right work—not to choose a financing product before the work is defined.
A failed system can make timing the deciding factor. West Heating & Cooling states that it offers 24/7 emergency service and repairs. That availability is relevant when you need the heating or cooling problem assessed promptly; it does not, by itself, establish that replacement is necessary or that financing is the best way to pay.
How to compare financing with paying from savings
Put the written replacement proposal beside the written financing agreement. You should be able to answer each of these questions without relying on a verbal summary:
- Confirm the scope. Which equipment and installation work does the proposal include? Ask about any related work that is excluded.
- Find the total repayment. Add the required payments and any disclosed fees. Compare that total with the amount you would pay without financing.
- Check the payment schedule. Identify when payments begin, when they are due, and whether the payment can change.
- Read every condition. Look for late-payment consequences, early-payoff terms, and any condition attached to a promotional offer.
- Protect your cash needs. Decide how much savings you need to retain for other household or business expenses before choosing to pay upfront.
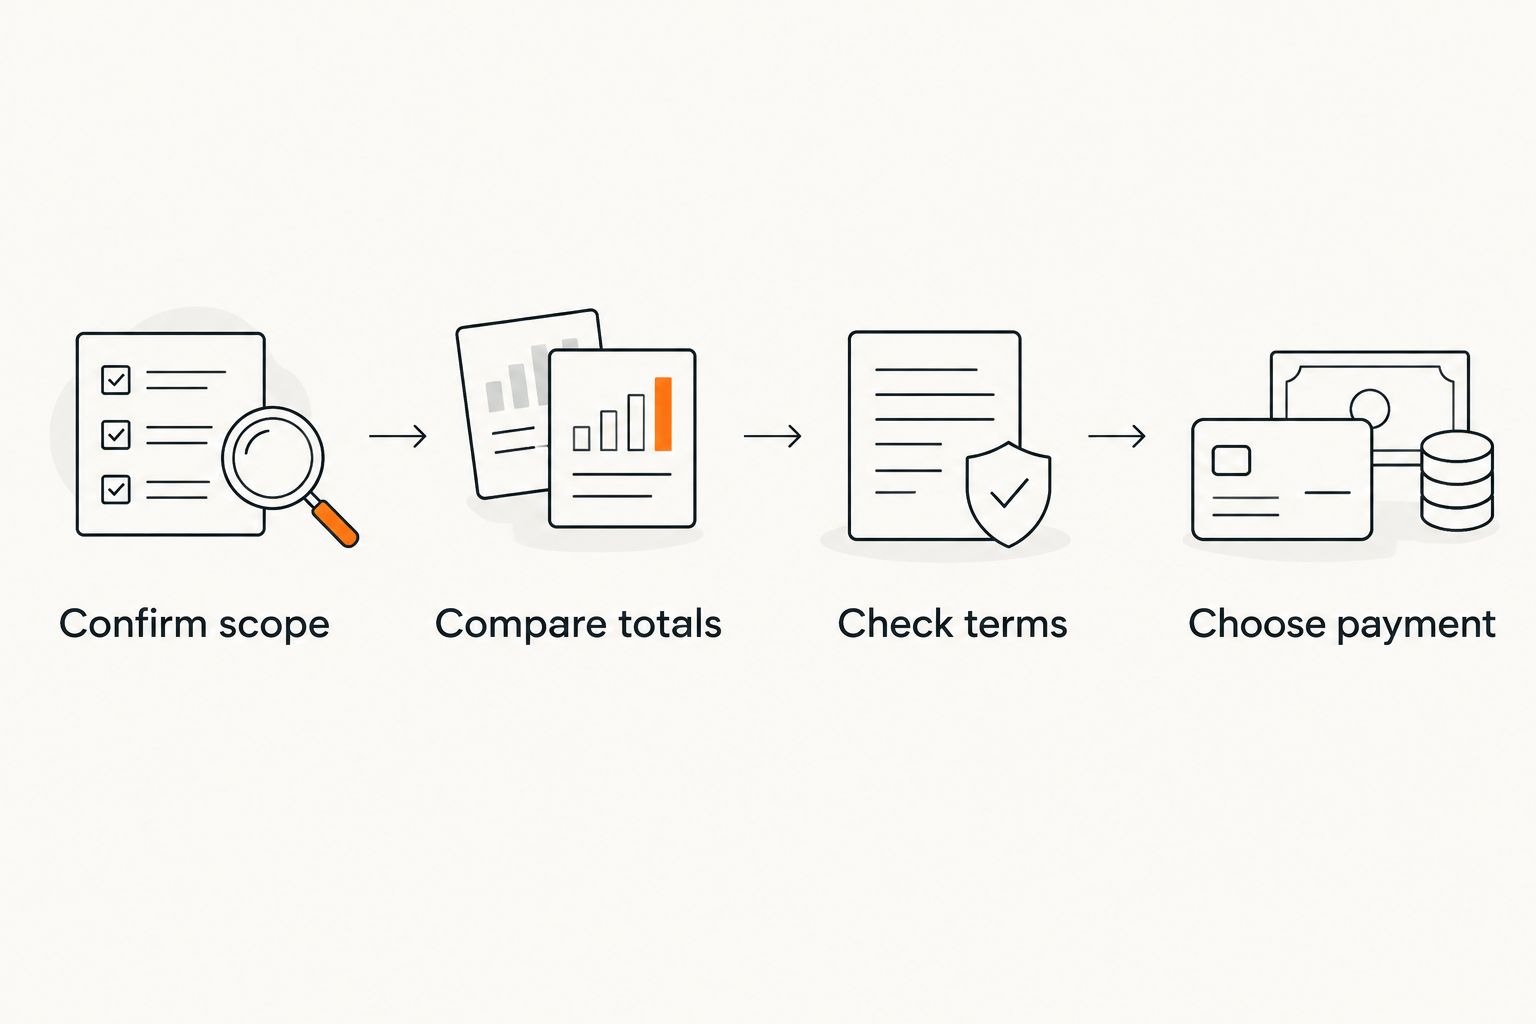
A monthly payment answers only one of those questions. It tells you what leaves your account on a schedule, not what the replacement will cost after borrowing charges. In 2026, use the written agreement—not a payment estimate—as the basis for that comparison.
Paying from savings avoids financing charges, but it is not automatically the better choice. If paying upfront leaves you unable to cover other necessary expenses, preserving some cash can matter more than avoiding interest. The answer depends on your own savings and the specific terms offered, not on a rule that fits every household.
When financing is the better fit
Financing is a reasonable choice when the replacement is necessary, delaying it does not meet your heating or cooling needs, and the full repayment fits alongside your other obligations. It can also let you keep cash available for expenses that cannot wait. Both conditions matter: an urgent replacement does not make an unaffordable agreement affordable.
Get the installation scope settled before comparing offers. If one proposal includes work another excludes, their payment figures do not describe the same project. Ask for clarification rather than choosing the smallest advertised payment.
For a residential system, consider how reliably the current furnace or AC serves the home while you make the decision. For a commercial system, consider the effect of interrupted heating or cooling on the space you operate. Those needs can affect when work must happen, but they do not replace a review of financing terms.
When financing is not worth it
Skip financing when the total repayment is too high for the benefit you receive. That includes an agreement with a manageable payment but a term or charges that make the overall obligation unacceptable to you.
Do not borrow for a full replacement just because the existing system needs attention. Ask whether repair is an appropriate option and what problem it would address. If repair meets your needs, you can compare that scope with replacement before committing to a loan.
Be equally careful with a promotional offer. Read the written conditions and confirm what happens if you do not meet them. A promotion is only useful if its terms work for your actual payment plan; do not treat its headline payment as the total cost.
Why HVAC financing terms vary
No single payment figure applies to every full system replacement. The terms and project scope both affect what you would repay:
- Work included: A furnace replacement and a proposal covering both a furnace and AC unit are different scopes.
- Amount financed: Paying part of the project upfront changes how much you borrow.
- Interest rate: The rate in the written agreement affects borrowing charges.
- Repayment length: Spreading payments over a longer term changes the schedule and can change the total interest paid.
- Fees and conditions: Disclosed fees and promotional requirements affect the full obligation.
- Payment structure: A fixed payment is easier to plan around than a payment that can change under the agreement.
Read these factors together. A longer term can make an individual payment easier to manage while increasing total borrowing charges. A proposal with a lower financed amount can still be a poor fit if the work you need is missing from its scope.
Should I finance a replacement or repair the system first?
Repair first when an assessment shows it will meet your heating or cooling needs. If the proposed repair does not resolve the underlying problem, compare its scope with a replacement proposal before choosing either option. In 2026, the useful comparison is the work each choice accomplishes and how you would pay for it—not the age of the equipment alone.
Ask what the repair would fix and what it would leave unchanged. Then ask what a full replacement would include. You need those answers before deciding whether a loan funds a necessary solution or a larger project than your situation requires.
Is a lower monthly HVAC payment a better deal?
No. A lower monthly payment is not a better deal unless the total repayment and terms also work for you. Check the payment schedule, borrowing charges, fees, and conditions before comparing offers. A payment that fits this month does not settle the question of what you will owe overall.
If two agreements cover the same installation, compare them using their written totals. If the installation proposals differ, resolve that difference first. Otherwise, you are comparing both the financing and the equipment scope at once.
What should I ask before signing in 2026?
Ask for the written installation scope and the full financing agreement. Confirm what work is included, the total you would repay, when payments begin, whether they can change, and what happens if you pay late or early. Keep the proposal and agreement together so the work being funded is clear.
If a term is unclear, get an explanation before signing. You should be able to describe both the system work and the repayment obligation in plain language. If you cannot, pause the decision until you can.
FAQ
Is HVAC financing worth it for a full system replacement in 2026?
Yes, when replacement is necessary and the full repayment fits your budget. Compare the written loan terms with paying from savings and ask whether repair can meet your needs first.
Should I finance a furnace and AC replacement together?
Finance them together only if both replacements are necessary and the complete proposal fits your budget. Confirm exactly which equipment and installation work the agreement covers.
Is paying cash better than HVAC financing?
Paying cash avoids borrowing charges, but it also reduces the savings you keep available. Compare the financing total with your need to retain cash for other expenses.
Does West Heating & Cooling offer HVAC financing?
The information provided does not establish that West Heating & Cooling offers financing. Ask the company directly about current payment arrangements and review any written terms before agreeing.
Can I finance an HVAC replacement during an emergency?
Financing can be an option if an offer is available and its terms fit your budget. West Heating & Cooling states that it provides 24/7 emergency service; ask for an assessment of the needed work before choosing how to pay.
What matters more, the monthly payment or total repayment?
Total repayment shows the full financing obligation; the monthly payment shows whether the schedule fits your budget. You need both figures from the written agreement.
Should I repair my HVAC system instead of replacing it?
Choose repair when an assessment shows it will meet your needs. Compare the proposed repair with the replacement scope before borrowing for a full system.
One last thing
In 2026, the strongest financing decision starts with a question about the equipment: What work is actually necessary? Once you have that answer in writing, compare the full repayment with what you can pay upfront. A clear installation scope keeps a financing decision from becoming a guess about the system itself.